






 Add Us On Google

When the One Big Beautiful Bill Act passed in July 2025, one of its most celebrated provisions was a new $6,000 deduction for taxpayers 65 and older, effectively eliminating federal taxes on Social Security benefits for most recipients. For anyone concerned about benefits for seniors, it was framed as a long-overdue win. For millions of retirees, it is a win, at least through 2028. But the same provision that reduces this year's tax bill is accelerating the timeline to a much larger problem, and the math on that trade-off is not close.
Both sides of the aisle collect Social Security, and the numbers do not change based on how you voted. The trade-off is what it is.
Now Available: The Definitive Guide to Retirement Income
Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.
That is exactly what The Definitive Guide to Retirement Income helps answer.1 <p class="">Investing in securities involves a risk of loss. Past performance is never a guarantee of future returns. Investing in foreign stock markets involves additional risks, such as the risk of currency fluctuations. Guides are provided by Fisher Investments. The publisher may be compensated when readers request a guide.</p> It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›
What the deduction actually saves
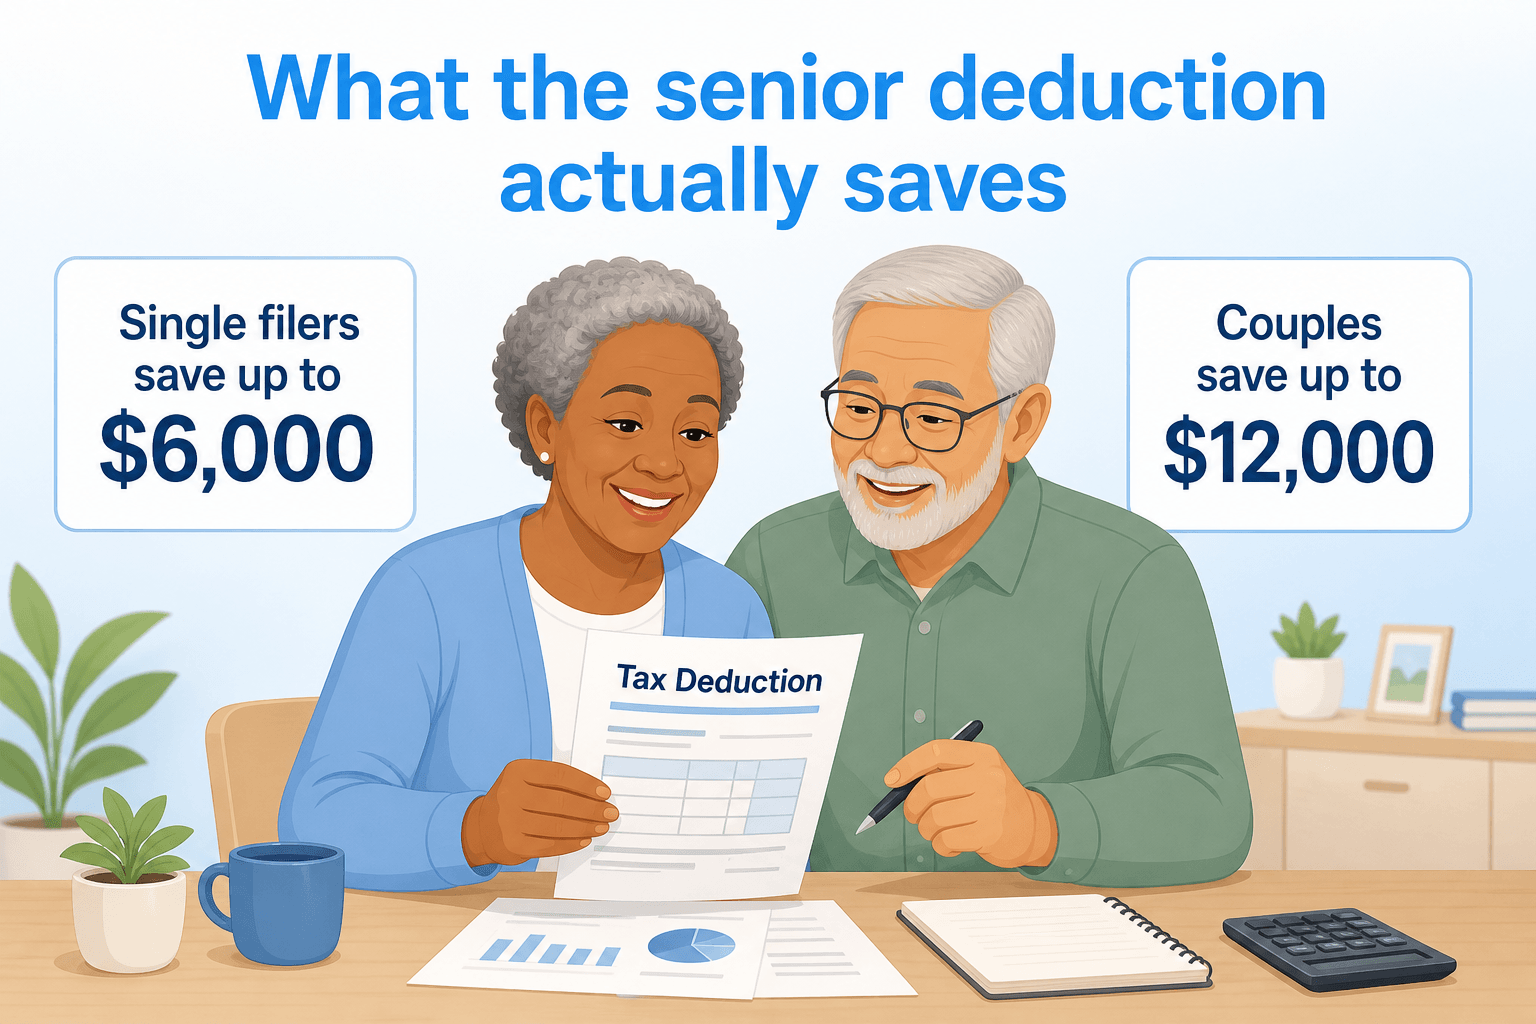
The senior deduction allows single filers aged 65 or older to deduct an additional $6,000 from taxable income for tax years 2025 through 2028. Married couples where both spouses qualify can deduct $12,000. The deduction phases out for single filers with MAGI above $75,000 and for joint filers above $150,000, disappearing entirely at $175,000 single and $250,000 joint.
For the average Social Security recipient, the practical tax savings is real but modest. The average monthly Social Security retirement benefit as of early 2026 is approximately $2,071, or about $24,852 per year. A single retiree receiving that amount in a typical income range would see their federal tax bill reduced by roughly $300 to $900 per year depending on their total income, tax bracket, and whether they were previously paying taxes on benefits at all.
Call it approximately $660 per year for a middle-income single retiree in the 22% bracket, multiplied across four years: roughly $2,640 in total tax savings before the deduction expires.
According to the Tax Policy Center, fewer than half of older adults will actually benefit from the new deduction. The lowest-income seniors often owe no taxes already, so the deduction reduces a bill that was already zero. The highest earners phase out of it. The benefit is concentrated in the middle.
What it costs the trust fund
Since 1984, income taxes paid on Social Security benefits have been routed directly back into the Social Security trust funds, not into general revenue. That was a deliberate design choice made as part of the 1983 reforms that saved the program from insolvency the last time it faced this situation. Under prior law, taxation of benefits was projected to contribute approximately $100 billion to the trust funds in 2025, growing to over $140 billion annually by 2027.
The OBBBA's senior deduction directly reduces that revenue stream. The Joint Committee on Taxation estimates the provision reduces federal revenues by $91 billion over four years. A portion of that reduction comes directly from the trust fund contributions that would otherwise have been made.
The SSA's Office of the Chief Actuary confirmed in a letter to Senator Ron Wyden dated August 5, 2025, that the OBBBA's total net increased cost to the Social Security program is $168.6 billion over calendar years 2025 through 2034, and that the OASI trust fund depletion date was accelerated from the first quarter of 2033 to the fourth quarter of 2032 as a direct result.
The depletion math: What 2032 means
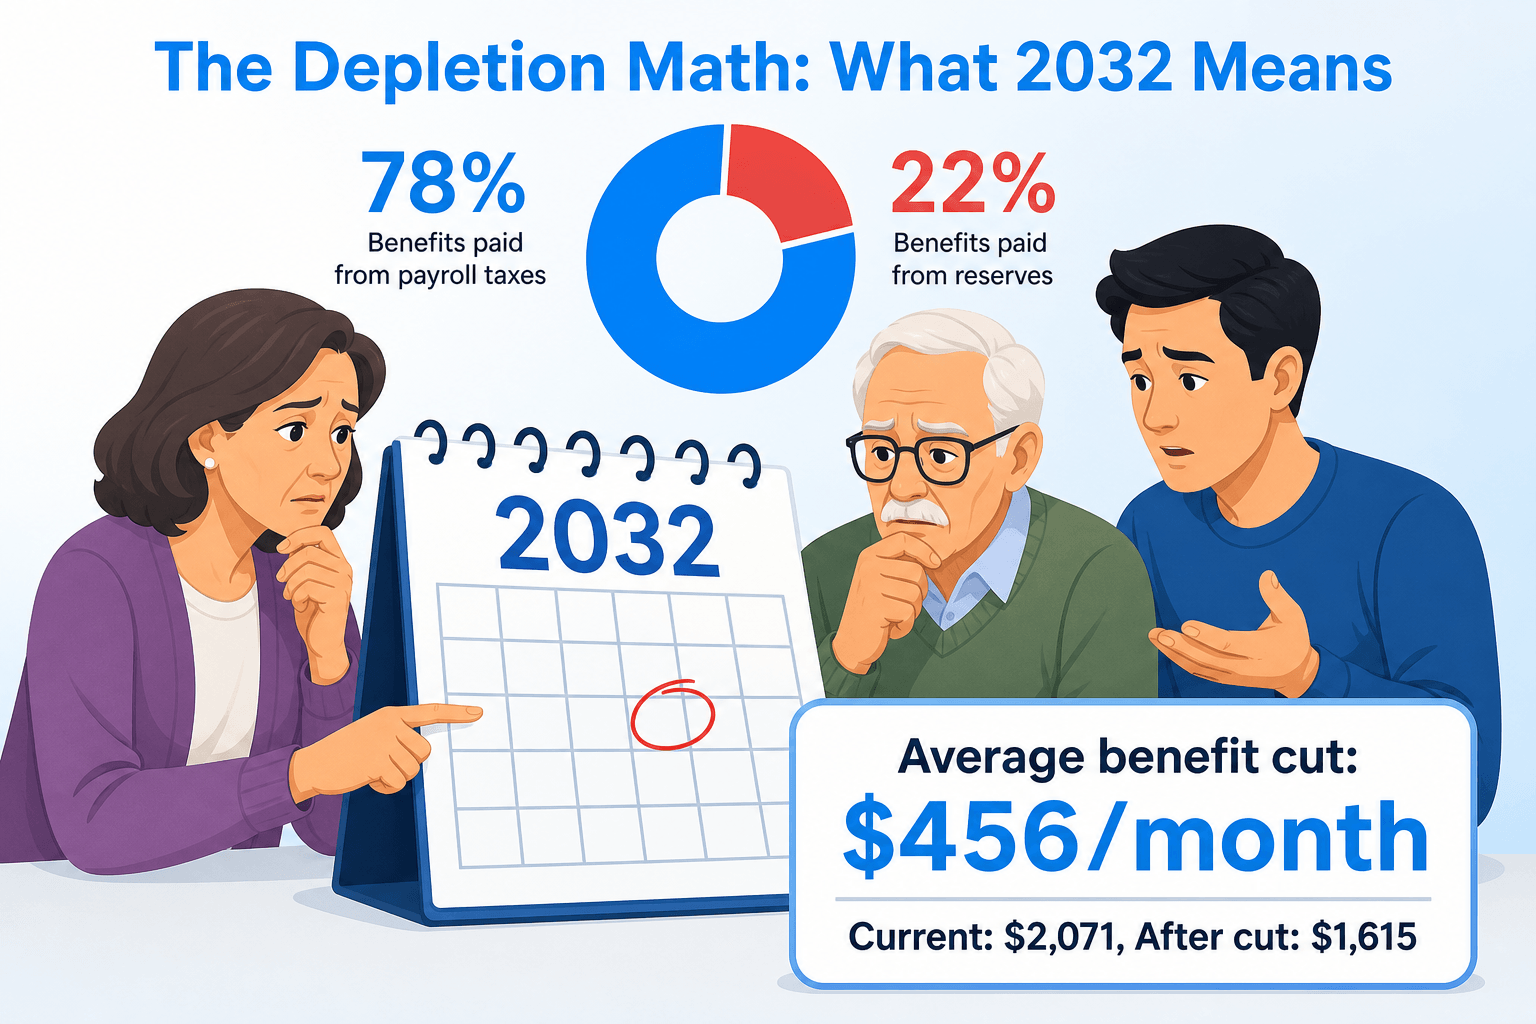
When the OASI trust fund runs out of reserves, Social Security does not stop paying benefits. But it can only pay what comes in from payroll taxes in real time, which is currently enough to cover roughly 78% of scheduled benefits. That means a 22% across-the-board cut, applied to every recipient, unless Congress acts before the deadline.
The average monthly benefit of $2,071 reduced by 22% is $2,071 minus $456, which equals $1,615 per month. That is $456 per month less than the current scheduled amount, every month, for the rest of the recipient's life.
Over 10 years, a single retiree would lose approximately $55,000 in cumulative benefit income. Over 20 years, more than $109,000.
Against that, the four years of tax savings from the senior deduction total roughly $2,640 for the same average retiree. Even at the maximum $6,000 deduction at the 22% bracket, four years of savings comes to about $5,280.
The comparison in plain terms: A few thousand dollars in tax savings through 2028, against tens of thousands of dollars in lost benefits starting in 2032 if the cut takes effect. The deduction lasts four years. The benefit cut, if it arrives, is permanent.
Released: The Definitive Guide to Retirement Income (Sponsor)
Most people spend their entire working lives focusing on one thing: growing a pile of money. Then they retire and discover the skill they actually need is close to the opposite. Turning that pile into steady income, year after year, through good markets and bad, without ever running out. It may be the least discussed and most consequential transition in personal finance, and plenty of otherwise careful investors walk into it with no real plan.
That is exactly what The Definitive Guide to Retirement Income helps answer.1 <p class="">Investing in securities involves a risk of loss. Past performance is never a guarantee of future returns. Investing in foreign stock markets involves additional risks, such as the risk of currency fluctuations. Guides are provided by Fisher Investments. The publisher may be compensated when readers request a guide.</p> It is a free guide from Fisher Investments covering what your retirement will really cost, where the cash flow should come from, and how much you can safely withdraw each year. Learn More Here ›
Two important caveats
Neither side of this trade-off is certain.
On the benefit cut: Congress has stepped in to protect Social Security before. In 1983, lawmakers passed reforms when the trust fund was just weeks away from insolvency. Given the political pressure to avoid a 22% benefit cut affecting 73 million people, many analysts expect Congress to act again. While the cuts would take effect under current law if nothing changes, they are not inevitable.
On the deduction: If Congress extends the senior deduction beyond 2028, the cost rises to approximately $220 billion over 10 years according to Joint Committee on Taxation projections, which would compound the trust fund pressure further. As currently written, the deduction expires after December 31, 2028, and financial planning for 2029 and beyond should not assume it continues without a specific act of Congress.
Bottom line
The senior deduction can save qualifying retirees money on taxes through 2028, but there is a trade-off. It also reduces money going into Social Security, potentially moving the trust fund closer to depletion. For someone living on just Social Security or relying on it for most of their income, a few years of tax savings may not be worth the risk of a future benefit cut.
Before making plans around the tax savings, look at how both scenarios could affect your own finances. Check your projected benefits and consider how a possible benefit cut would affect your retirement budget. Your individual income, tax bracket, and Social Security benefit will determine how much you could actually gain or lose.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.


- Huge discounts on travel, groceries, prescriptions and more
- Access to financial planning resources and health tools
- Join AARP and get 25% off with automatic renewal








