



 Add Us On Google

When you earn a regular paycheck, Social Security taxes can feel like a year-round fact of life. For some of the country's highest earners, though, those taxes stop once their income reaches the annual wage cap.
A bipartisan Senate proposal wants to change that by making high earners pay Social Security taxes on all of their wages. The idea could bring trillions of dollars into the program and help protect future senior benefits as lawmakers look for ways to shore up Social Security.
Get a protection plan on all your appliances
Did you know if your air conditioner stops working, your homeowner’s insurance won’t cover it? Same with plumbing, electrical issues, appliances, and more.
A home warranty from Choice Home Warranty could pick up the slack where insurance falls short.
For a limited time, you can get your first month free with a Single Payment home warranty plan.
How the payroll tax cap works right now
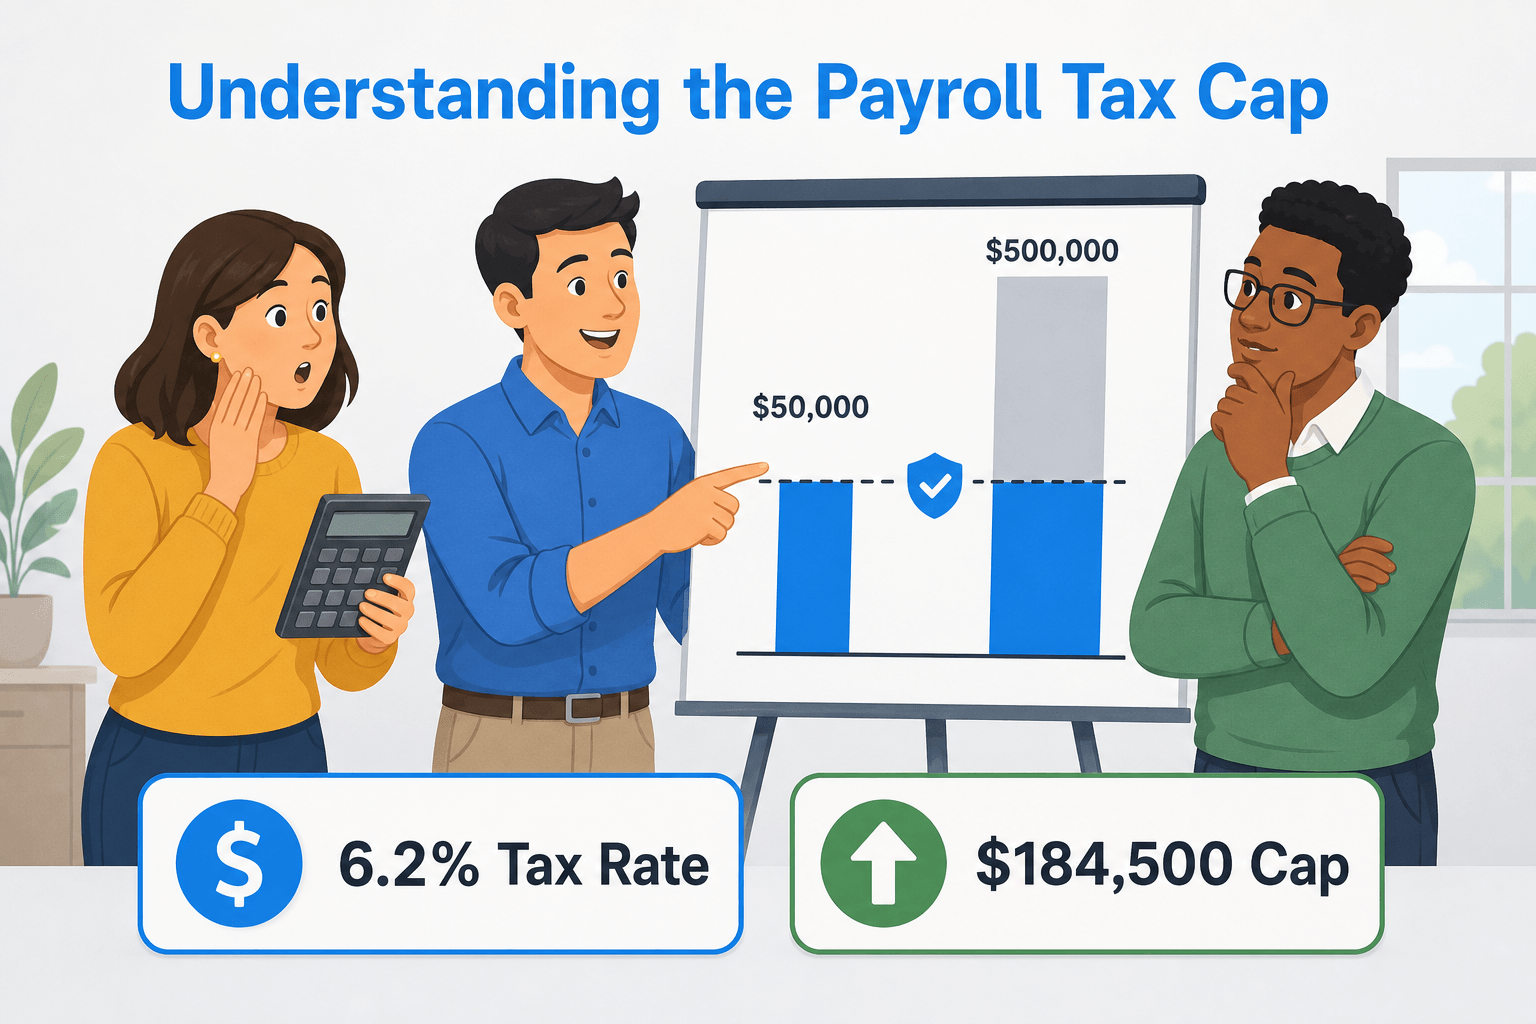
You and your employer each pay 6.2% of your wages into Social Security, but only up to a yearly limit. In 2026, that limit is $184,500, so once your earnings pass that amount, Social Security taxes stop for the rest of the year.
Someone earning $50,000 pays the tax on every dollar they make. In contrast, someone earning $500,000 pays it only on the first $184,500, leaving the remaining $315,500 outside the Social Security tax.
At most, an employee pays about $11,400 into Social Security in 2026, whether they earn $184,500 or several million dollars. Most workers never hit the cap, so they keep paying the tax on all of their wages throughout the year.
What the bipartisan proposal would change
Sens. Elizabeth Warren and Bernie Moreno want to remove the $184,500 ceiling so every dollar of wages is subject to Social Security tax, just like it already is for Medicare. They estimate the change would bring in roughly $3 trillion in extra revenue over 10 years.
The idea also has support from voters in both parties, with a Bipartisan Policy Center poll finding that 65% of Democrats and 62% of Republicans favor applying the Social Security tax to all wages.
That said, the bill is still being drafted and hasn't been formally introduced as legislation. Warren and Moreno have said it could extend Social Security's solvency "for another generation," although how much extra time it buys would depend on the final bill.
How the proposal would affect the highest earners
A worker earning $1 million a year would see a much bigger Social Security tax bill under the proposal. Instead of paying about $11,400, the worker would pay roughly $62,000, with the employer contributing the same amount.
The extra tax would apply only to earnings above today's limit, so workers below $184,500 would not pay more under the proposal.
High earners also would not get a larger retirement benefit in exchange for those extra contributions. The additional money would go into Social Security to help strengthen the program rather than increase the maximum benefit available to people with very high incomes.
If you’re over 50, take advantage of massive discounts and financial resources
Over 50? Join AARP today— because if you’re not a member you could be missing out on huge perks. When you start your membership today, you can get discounts on things like travel, meal deliveries, eyeglasses, prescriptions that aren’t covered by insurance and more.
Start your membership by creating an account here and filling in all of the information (Do not skip this step!) Doing so will allow you to take up to 25% off your AARP membership, making it just $15 the first year with auto-renewal.
The reason high earners would pay more without getting more
Social Security's latest published estimates show that removing the wage cap without giving additional benefit credit could close about 67% of the program's long-term funding gap. If those newly taxed earnings also increased future benefits, the improvement would fall to roughly 48%.
In other words, the proposal gets much more mileage out of the new tax revenue by leaving the benefit formula alone.
How far this plan could push back the funding deadline
CBO has looked at a similar proposal that would tax earnings above $250,000 and estimated that it could push the combined trust fund's depletion date to around 2051.
That could buy Social Security another 15 to 20 years before its reserves run short. It would not solve the entire funding problem, but it could give lawmakers much more time to deal with what remains instead of facing a deadline that is much closer.
What the proposal means for most workers
If you earn less than $184,500, which is the case for about 94% of American workers, the proposal would not change your tax bill by a single dollar. You already pay the tax on all of your wages, so there would be nothing extra coming out of your paycheck.
What would change is how secure your future benefits are. More revenue flowing into the trust fund could help the program pay scheduled benefits for longer, which reduces the likelihood of the automatic 22% cut that current law would trigger when the retirement trust fund runs out.
The proposal essentially asks the highest-earning 6% to contribute on the same basis everyone else already does, with the goal of keeping the program funded for the people who depend on it most.
Retirement News: Almost 80% of Americans fear a retirement age increase — here’s the real reason why
What Congress would still have left to fix
Even if the plan closed most of Social Security's funding gap, Congress would still need another fix for the portion that remains. Future changes could involve benefits or the retirement age, depending on what lawmakers ultimately agree to.
The proposal also applies only to wages, so investment income and capital gains would still be left out of the Social Security payroll tax. It would not fix every part of the program's finances, but it could leave Congress with a much smaller problem to solve.
Bottom line
The Warren-Moreno proposal is one of the simplest and most popular ideas for extending Social Security's life. It asks high earners to pay into the system on the same terms everyone else already does, and it would close a large share of the program's long-term shortfall without reducing anyone's scheduled benefit.
For your own retirement plan, it still makes sense to treat any future reform as a possibility rather than something guaranteed. If a proposal like this eventually becomes law, it could make the outlook for future benefits a lot less worrying, which would be good news for anyone counting on Social Security later in life.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.


- Huge discounts on travel, groceries, prescriptions and more
- Access to financial planning resources and health tools
- Join AARP and get 25% off with automatic renewal