Add Us On Google

If you're 81 or comparing your senior benefit to someone who is, a single average number can be tempting to treat as a verdict. It isn't. Social Security benefits vary enormously from person to person, shaped by decades of earnings, the age someone claimed, and years of cost-of-living adjustments (COLA) that compound differently for everyone.
Before drawing any conclusions about how your own check stacks up, it helps to understand what this average actually measures, who it includes, and why it can mask more than it reveals. Here's what the data shows, and how to read it honestly.
Get a protection plan on all your appliances
Did you know if your air conditioner stops working, your homeowner’s insurance won’t cover it? Same with plumbing, electrical issues, appliances, and more.
A home warranty from Choice Home Warranty could pick up the slack where insurance falls short.
For a limited time, you can get your first month free with a Single Payment home warranty plan.
The average benefit for 81-year-olds, according to SSA data
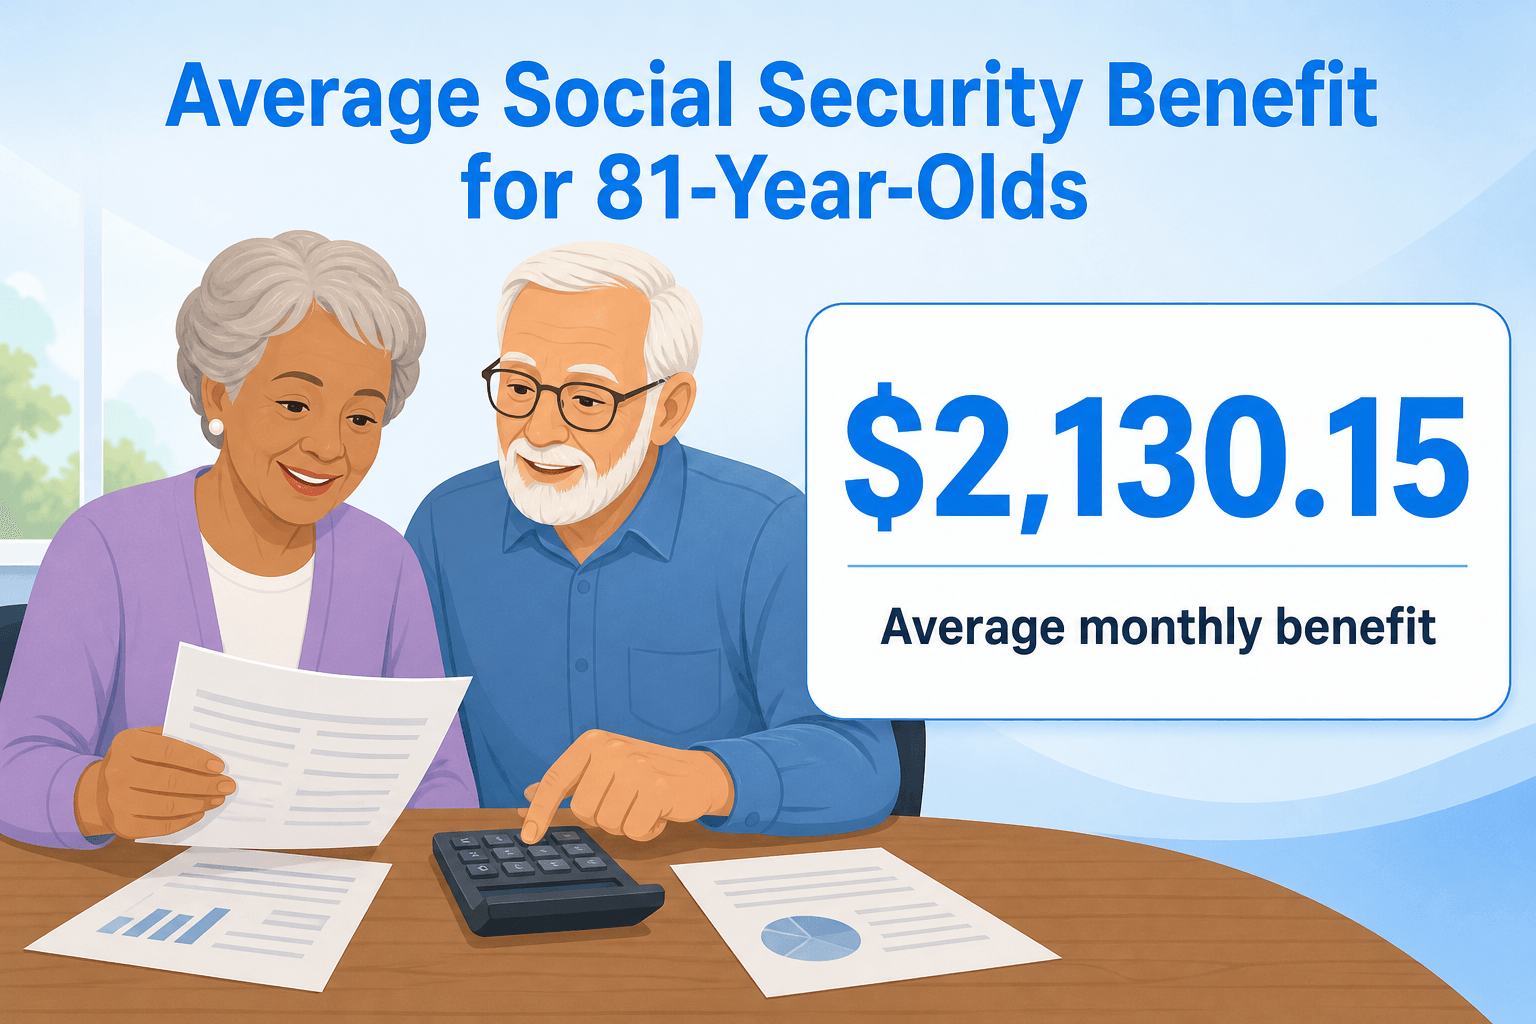
As of December 2025, the average Social Security retired-worker benefit for 81-year-olds was $2,130.15 per month, according to the Social Security Administration's official beneficiary data. That figure covers non-dually-entitled retired workers, meaning people receiving benefits based on their own earnings record rather than a spouse's or survivor's benefit.
It's important to sit with the word "average" here, not "median." An average can be pulled upward by a smaller number of high earners who worked long careers at or near the maximum taxable income. A median, the point where half of recipients fall above and half below, often paints a more modest picture for a typical retiree. SSA's published data for this age group is presented as an average, so it likely overstates what a "typical" 81-year-old actually receives.
Men and women see very different averages
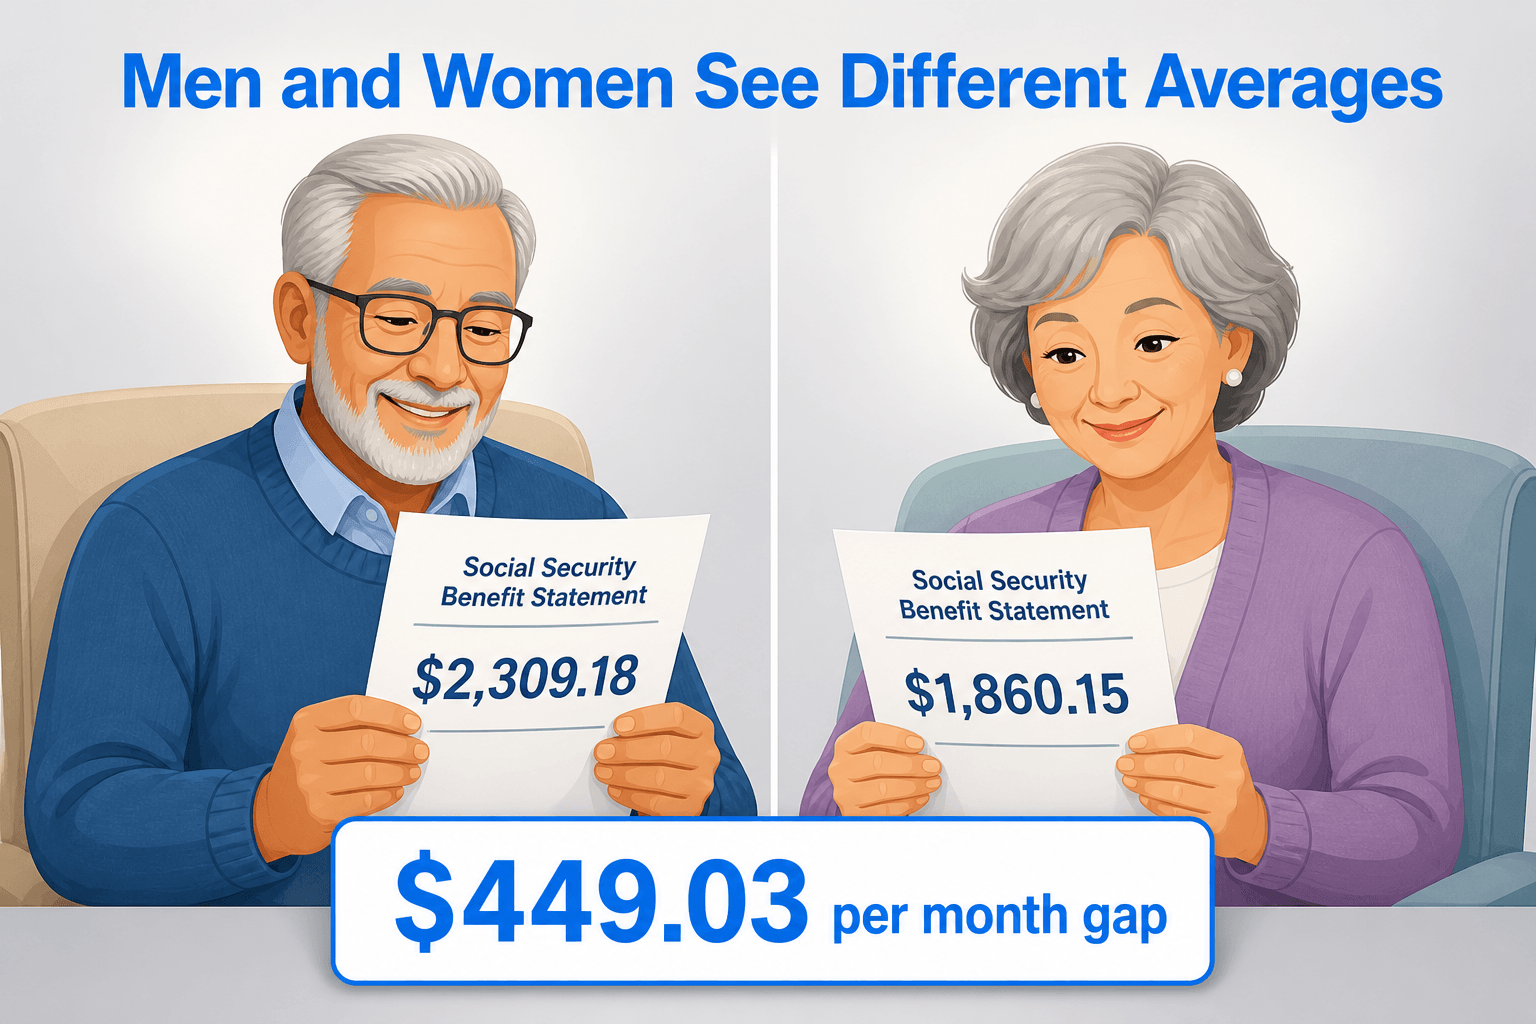
Blending men's and women's benefits into one number hides a real and persistent gap. At age 81, among non-dually-entitled retired workers, SSA reports:
- Men: $2,309.18 per month average
- Women: $1,860.15 per month average
That's a difference of about $449.03 a month, or roughly $5,388 a year, according to SSA's December 2025 figures. This gap shows up consistently across nearby ages too. At 80, men averaged $2,320.01 versus $1,878.72 for women. At 82, men averaged $2,304.74 versus $1,841.99 for women.
The reasons behind this gap are well documented. Social Security benefits are calculated from a worker's 35 highest-earning years, adjusted for wage growth over time, a figure the SSA calls average indexed monthly earnings (AIME). Women in this generation often had lower lifetime earnings than men, took more time out of the workforce for caregiving, or worked part-time for stretches that lowered their 35-year average.
SSA's own research notes that median earnings for women aged 15 to 64 working full-time were substantially lower than men's in recent decades, and that gap flows directly into benefit calculations decades later. Longer average life expectancies for women also mean more women in this age bracket are receiving reduced benefits from having claimed earlier, or survivor and dually-entitled benefits calculated differently than a standalone retired-worker benefit.
These numbers reflect retired-worker benefits only
It's worth being precise about what this average does and doesn't include. The $2,130.15 figure, and the separate men's and women's averages, apply specifically to non-dually-entitled retired-worker benefits, checks based on a person's own earnings history alone. They don't reflect spousal benefits (paid to a spouse based on a worker's record), survivor benefits (paid to a widow or widower), or dually-entitled benefits (paid to retired workers who also qualify for a higher benefit on another person's record).
Those benefit types are calculated differently and have their own separate averages. If you or someone you're comparing against receives a spousal, survivor, or dually-entitled benefit, this retired-worker average isn't the right benchmark.
If you’re over 50, take advantage of massive discounts and financial resources
Over 50? Join AARP today— because if you’re not a member you could be missing out on huge perks. When you start your membership today, you can get discounts on things like travel, meal deliveries, eyeglasses, prescriptions that aren’t covered by insurance and more.
Start your membership by creating an account here and filling in all of the information (Do not skip this step!) Doing so will allow you to take up to 25% off your AARP membership, making it just $15 the first year with auto-renewal.
Why one person's benefit can look nothing like the average
Even within the pool of retired workers, individual benefits vary widely for a few clear reasons.
Earnings history
Social Security calculates benefits from the 35 years in which a worker earned the most, indexed for wage growth. Someone who worked steadily near or above the taxable maximum for three-plus decades will land far above the average.
Someone with gaps in employment, part-time years, or lower wages throughout their career will land below it. For 2026, the Social Security taxable maximum, the most earnings subject to Social Security tax in a given year, is $184,500, according to the SSA.
Age at claiming
The age someone first claimed benefits has a lasting effect. Claiming as early as age 62 permanently reduces the monthly amount, while delaying past full retirement age (FRA, the age at which someone qualifies for 100% of their calculated benefit) increases it through delayed retirement credits, worth roughly 8% per year up to age 70, according to the SSA. Full retirement age is 67 for people born in 1960 or later, but for today's 81-year-olds, born around 1944 or 1945, FRA was 66.
Someone who claimed at 62 decades ago is still living with that reduction today; someone who waited until 70 locked in a permanently higher check. The maximum possible benefit for someone who delays claiming until age 70 is $5,181 per month in 2026, according to the SSA, though very few retirees actually qualify for that top amount.
Retirement News: Almost 80% of Americans fear a retirement age increase — here’s the real reason why
Years of COLA adjustments
Every benefit, once established, grows over time through annual cost-of-living adjustments. Someone who has been collecting benefits for 20 years has had two decades of COLA increases compound on top of their original amount, while someone who just claimed has had none yet.
The COLA for 2026 is 2.8%, following a 2.5% increase in 2025, according to SSA's announcement. Small annual increases compound meaningfully over a couple of decades, which is part of why average benefits shift gradually as a cohort ages.
What this comparison should (and shouldn't) tell you
If your own benefit, or a loved one's, doesn't match the average for their age, that's not necessarily a red flag. It usually just reflects a different earnings history, a different claiming age, or a different number of years of COLA increases stacked on top of the starting benefit. The average is a data point, not a target and not a judgment about whether someone made the "right" choices.
A more useful exercise is understanding your own numbers. The SSA's average retired-worker benefit for all ages combined, including both dually- and non-dually-entitled workers, was $2,071.30 per month as of December 2025, according to the agency's data, giving another reference point beyond the age-81 figure. But the most relevant number for your own planning is your personal benefit estimate, not any national average.
How to find your actual numbers
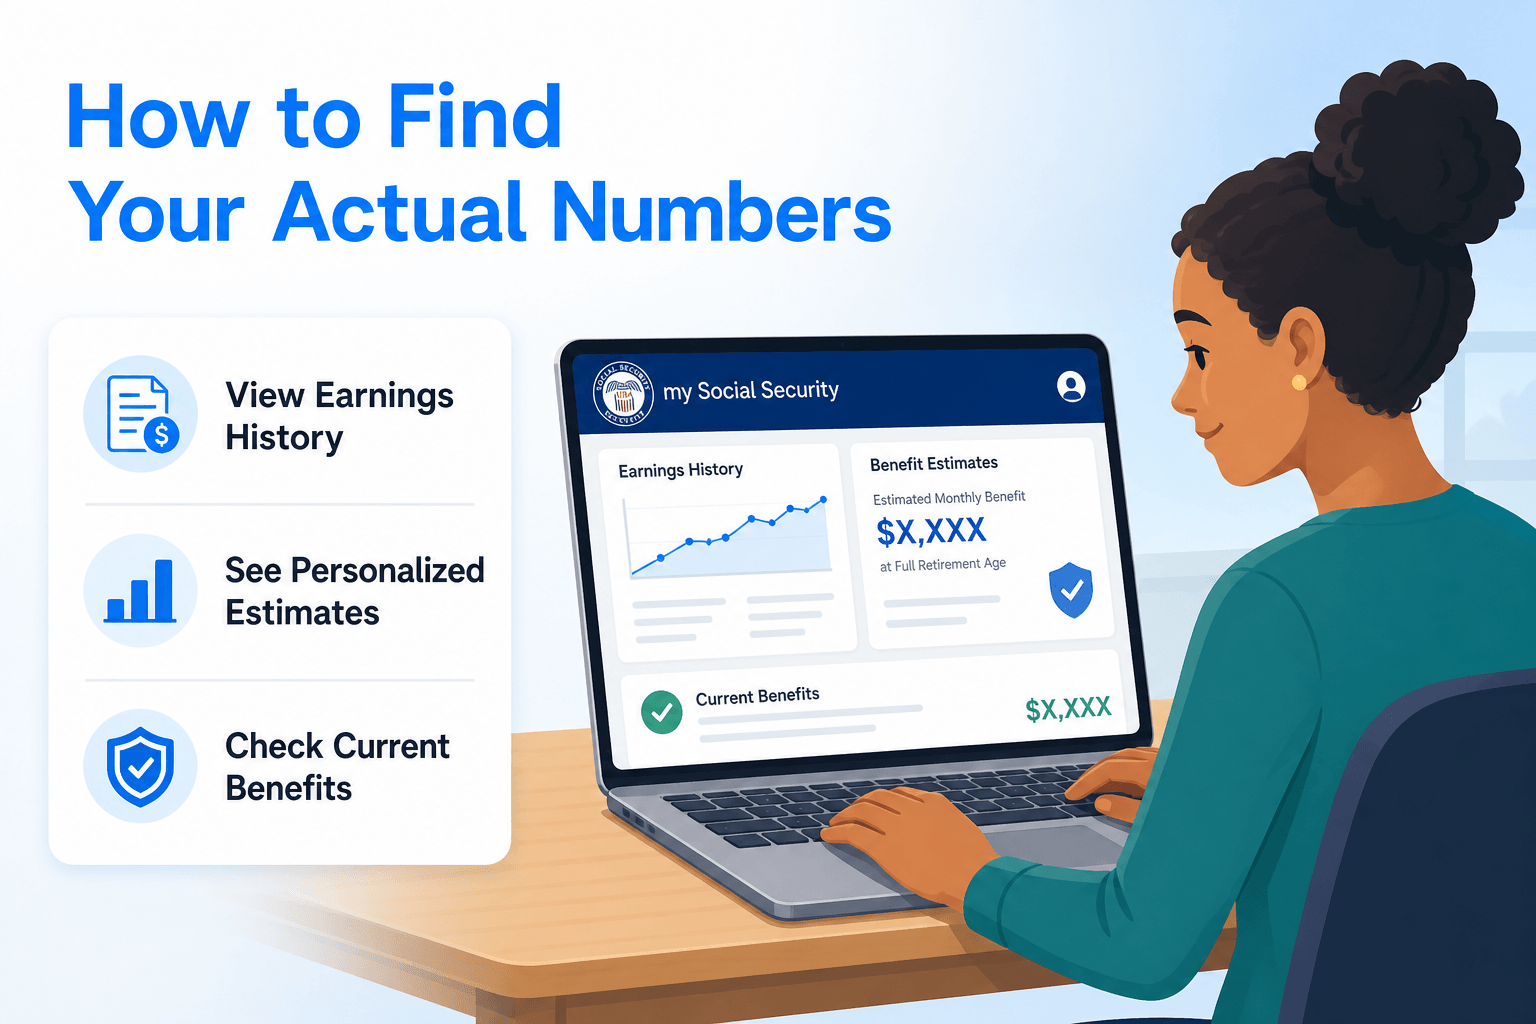
The SSA offers a free tool for exactly this purpose: a personal my Social Security account at ssa.gov. Once you create an account, you can view your full earnings history, see personalized estimates for claiming at different ages, and check your current benefit amount if you're already receiving payments. This is far more useful than any age-based average, because it reflects your specific work record and choices.
This article is intended as general information about how Social Security data works, not personalized financial advice. Decisions about when to claim benefits or how to plan retirement income can benefit from a conversation with a financial advisor or a review of your options directly through the SSA.
Get instant access to hundreds of discounts
Over 50? Join AARP today— because if you’re not a member you could be missing out on huge perks like discounts on travel, dining, and even prescriptions.
Get 25% off membership — just $15 for your first year with auto-renewal — and a free gift if you join today.
Bottom line
The average Social Security benefit for 81-year-old non-dually-entitled retired workers, $2,130.15 per month as of December 2025 according to the SSA, is a useful data point, but it's not a personal verdict of where you stand financially. The gap between men's and women's averages at this age, roughly $449 a month, reflects real historical differences in earnings and career paths, not something wrong with either group's benefit.
Rather than measuring yourself against a national average, the more productive step is understanding how your own earnings history, claiming age, and years of COLA increases have shaped your specific benefit, and how that fits alongside pensions, savings, and other income in your overall retirement picture.
FAQs
Why might my Social Security benefit differ from the average?
Your payment depends on your 35 highest-earning years, the age you began claiming, and the COLAs applied since then. Employment gaps, lower lifetime earnings, or claiming before full retirement age could result in a smaller benefit.
Does the average include spousal and survivor benefits?
No. The $2,130.15 average applies only to non-dually-entitled retired workers. Spousal, survivor, and dually-entitled benefits are calculated differently and aren't included in this figure.
Is the average Social Security benefit the same as the typical benefit?
Not necessarily. The SSA figure is an average, which can be pulled higher by retirees with large monthly benefits. A median would better represent the midpoint, but the SSA data cited here doesn't provide a median benefit specifically for 81-year-olds.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.


- Huge discounts on travel, groceries, prescriptions and more
- Access to financial planning resources and health tools
- Join AARP and get 25% off with automatic renewal