






 Add Us On Google

51 is a significant milestone for many reasons, including as a checkpoint for your finances. Are you on track? Are you behind?
While each situation is different, we can share the Federal Reserve's most recent data on what others have saved up. Use it to review your own progress and measure how far you need to build real wealth and hit your ideal net worth number.
Now Available: The Definitive Guide to Retirement Income
Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.
That is exactly what The Definitive Guide to Retirement Income helps answer.1 <p class="">Investing in securities involves a risk of loss. Past performance is never a guarantee of future returns. Investing in foreign stock markets involves additional risks, such as the risk of currency fluctuations. Guides are provided by Fisher Investments. The publisher may be compensated when readers request a guide.</p> It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›
Median net worth for 51-year-olds
The Federal Reserve doesn't have a number specifically for age 51, but the 45-54 age bracket is a good starting point. The average household or family net worth for this age range is $971,270 and includes everything a household owns minus what it owes.
But the median number of $246,700 may be more meaningful than the average, since it shows half of households making more than $246,700, and half making less. The mean would be dramatically higher, since it's pulled up by very wealthy households, but may be less reasonable to compare yourself to.
What the trends tell us
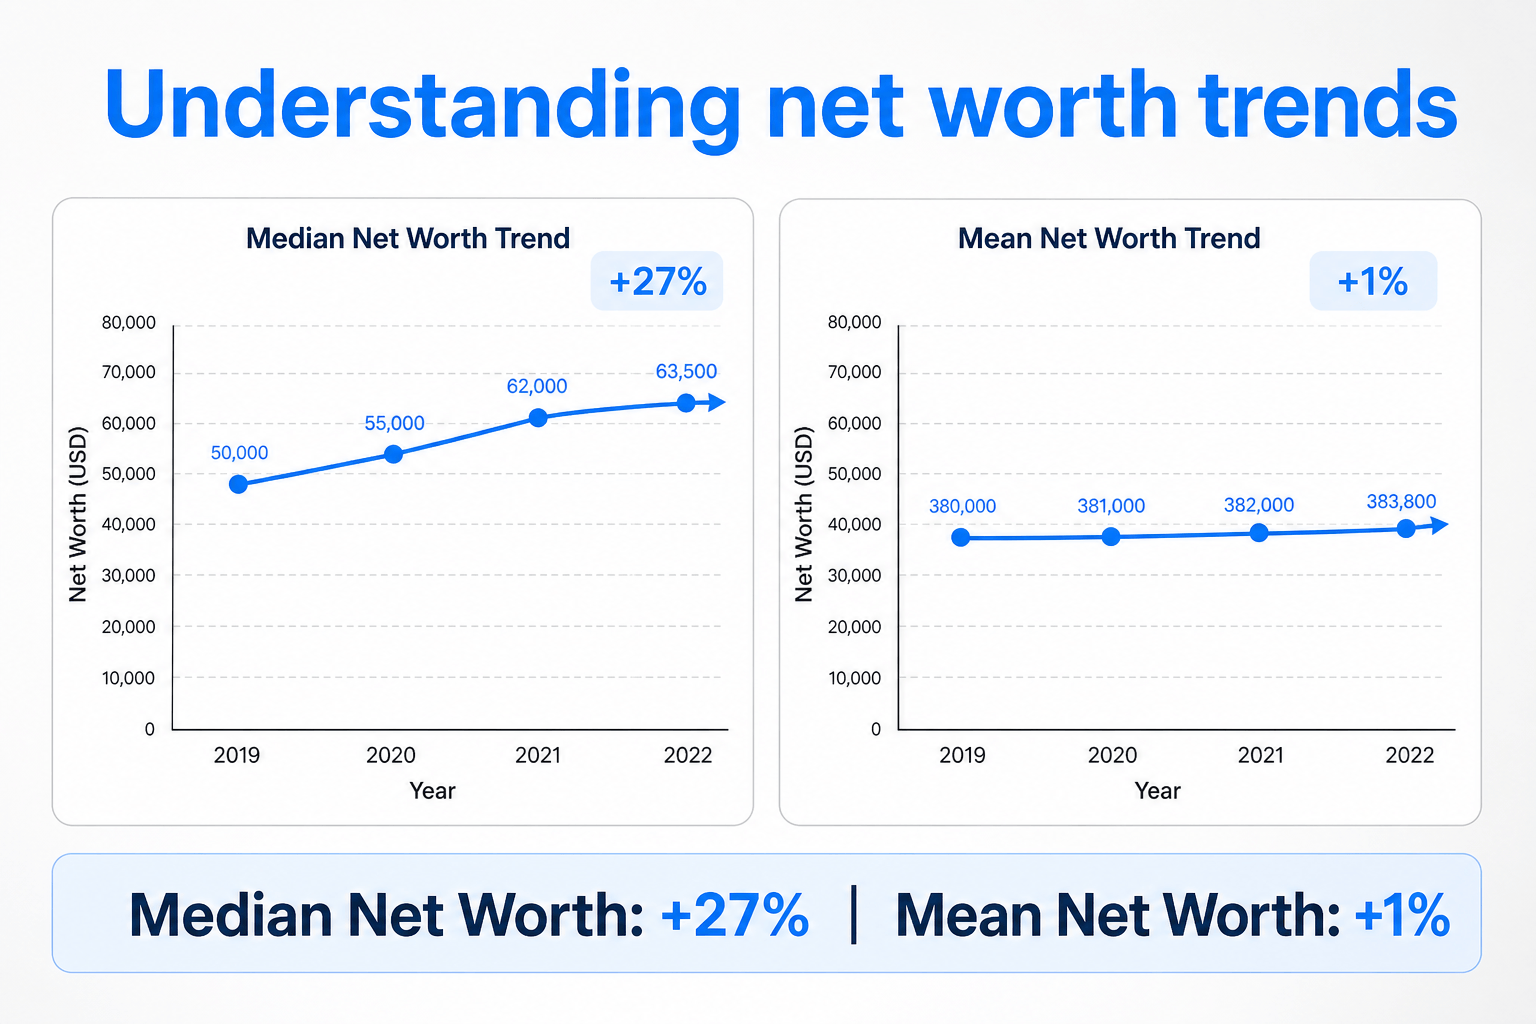
One important takeaway may be that comparison-driven anxiety over net worth shouldn't revolve around numbers alone; someone isn't doing poorly just because they aren't hitting that almost million-dollar average.
But perhaps more revealing than the "median vs. mean" data is how the numbers have changed over time. The median net worth for this age group increased 27% from 2019 to 2022, but the mean (average) only rose 1%.
Both figures are adjusted for inflation for that year's purchasing power and may show that net worth for the highest earners hasn't changed as much as it has for the rest of the population.
Peak earning years don't guarantee wealth
Households with a reference person in the 45-54 age bracket had the highest median before-tax family income of all the age groups in the report ($91,880). This was somewhat higher than the $86,470 for ages 35-44 and $82,150 for ages 55-64.
But income doesn't always translate into higher net worth, especially when expenses like paying for children's college costs, paying down mortgages, finishing up student loans, or caregiving for aging parents can eat into the budget. So, while income and net worth can be related, they don't typically move in lockstep.
Released: The Definitive Guide to Retirement Income
Most people spend their entire working lives focusing on one thing: growing a pile of money. Then they retire and discover the skill they actually need is close to the opposite. Turning that pile into steady income, year after year, through good markets and bad, without ever running out. It may be the least discussed and most consequential transition in personal finance, and plenty of otherwise careful investors walk into it with no real plan.
That is exactly what The Definitive Guide to Retirement Income helps answer.1 <p class="">Investing in securities involves a risk of loss. Past performance is never a guarantee of future returns. Investing in foreign stock markets involves additional risks, such as the risk of currency fluctuations. Guides are provided by Fisher Investments. The publisher may be compensated when readers request a guide.</p> It is a free guide from Fisher Investments covering what your retirement will really cost, where the cash flow should come from, and how much you can safely withdraw each year. Learn More Here ›
Where wealth is usually held
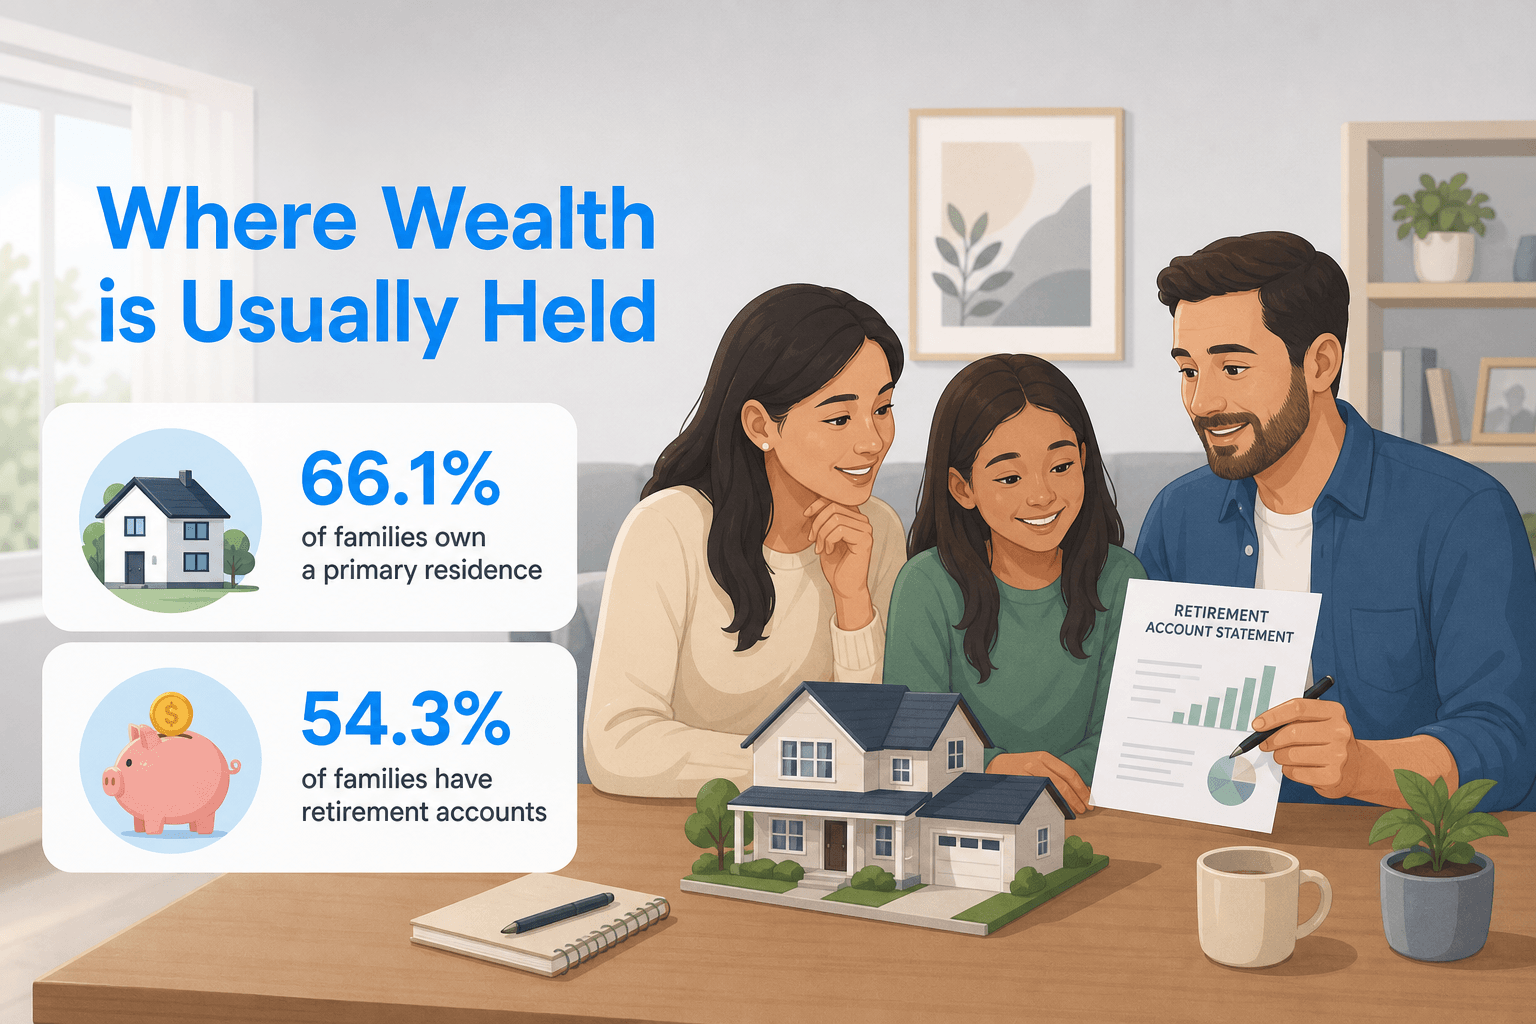
Net worth can include many asset types, so you can't assume that it's mainly liquid cash or stocks. Many middle-income households have their net worth tied up in homes or retirement accounts, something that's not easily accessible if they need it.
In 2022, 66.1% of all families owned a primary residence, and median net housing value was $201,000. Retirement accounts were also among the commonly held financial asset category, held by 54.3% of families. Among account holders, the median value was $86,900.
Liquid funds in transaction accounts like checking or savings were held by many, but the median balance was just $8,000.
How housing trends affect net worth
Rising home equity can have an outsized influence on balance sheets. An increase in home value due to inflation or rising home values in the surrounding area can raise net worth, even if the household hasn't truly experienced any more cash wealth.
For example, if your house suddenly has a new valuation that is $50,000 more than last year, your budgeting tool may reflect this in your final "net worth" metric. However, it's not new money you get to spend.
Why 50s matter so much
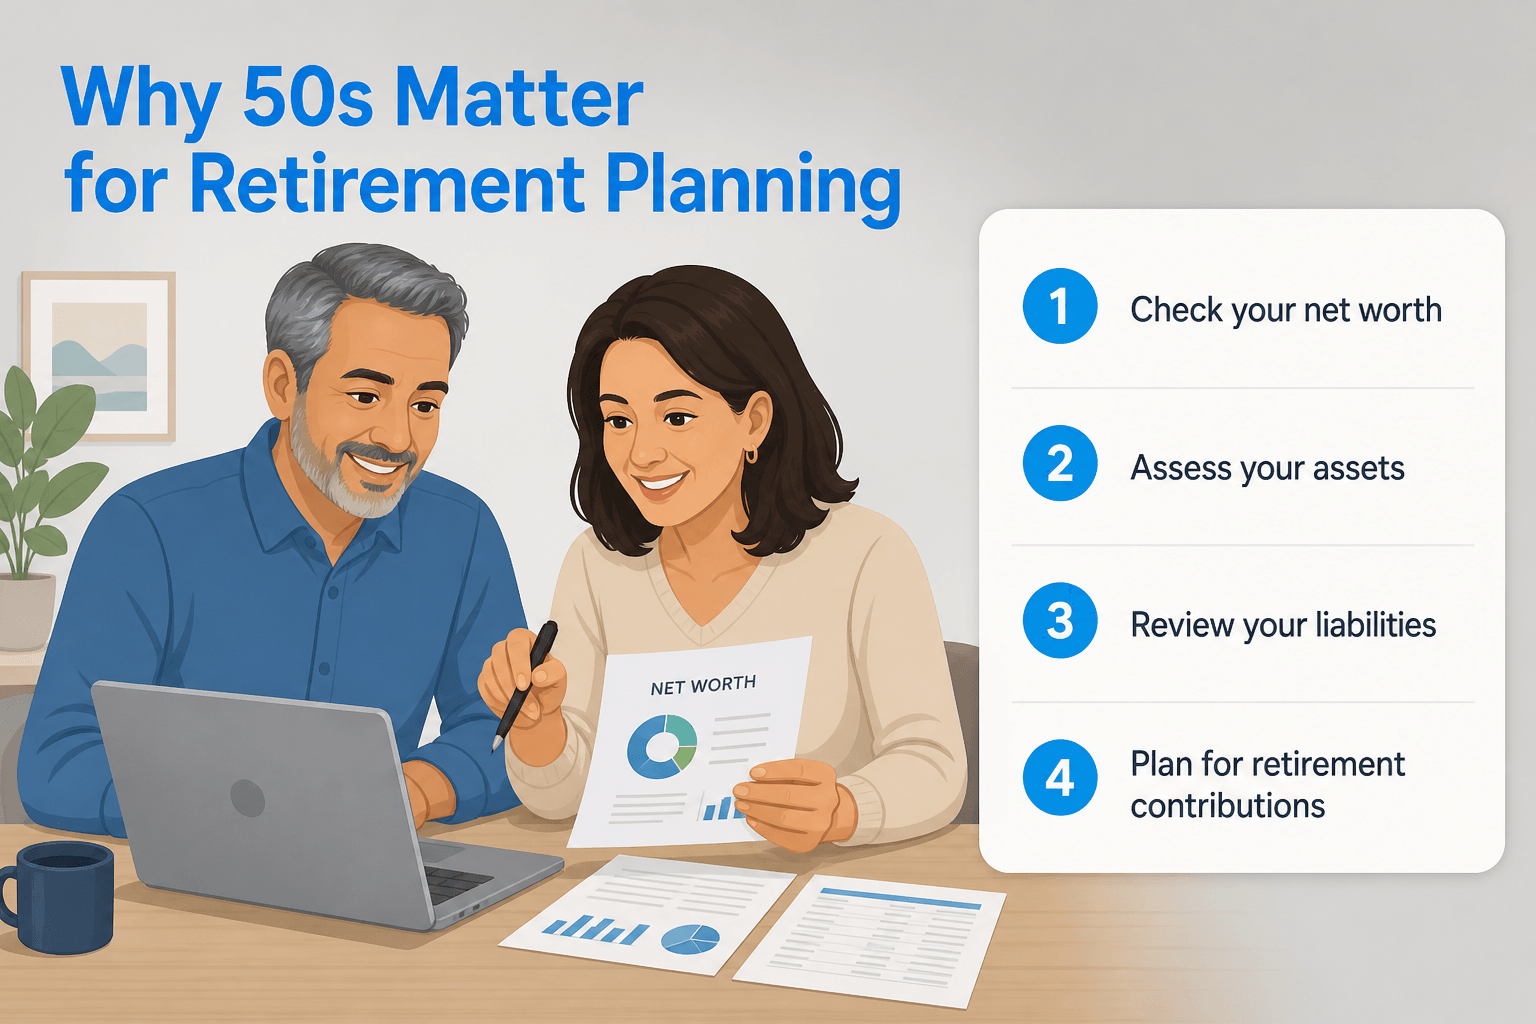
This age may be the final checkpoint to see if you're on track for retirement while you can still do something about it. It's very likely you're still working and can make continued contributions to your investments.
If you haven't done a net worth checkup in some time, start now. Add up all your assets, including vehicles, business interests, and liquid assets. Then, subtract liabilities, including any debt you owe on houses, cars, student loans, or credit cards.
Review this final number alongside monthly retirement contributions, high-interest debt, and expected required spending to see where you stand. Make sure you don't count home equity as spendable cash, even though it's included in your net worth figures.
Act now to boost savings rate
With your net worth number in hand, ask yourself, "Am I increasing my retirement contributions as my income rises?" rather than "Am I behind or ahead of the average net worth?"
The first question is more useful and helps you frame next steps:
- Check your employer match to maximize investments
- Review asset allocation and investment fees
- Pay down high-interest debt
- Build or fortify your emergency fund
- Update retirement income assumptions and beneficiaries
Each of these steps puts you in a better position for the future and can make your net worth progress more meaningful. If you need help, enlist a qualified financial advisor who can put these figures in context with your eventual retirement withdrawals and tax strategy.
Bottom line
$246,700 is the median net worth benchmark for households in the 45–54 age group, while $971,270 is the skewed average. But whether you more closely match the bigger number or the smaller one, it may be a less important metric for financial fitness than if you've established a healthy savings rate.
The share of gross income going toward retirement and other long-term savings matters, perhaps now more than ever. It's actionable, and unlike watching net worth numbers, measures a current habit you can adjust in real-time to ensure the next decade of financial decisions is more intentional.
FAQs
Is the median or average net worth more useful?
The median is generally a more realistic benchmark because extremely wealthy households can pull the average much higher. Still, neither figure determines whether you're personally prepared for retirement.
What should be included when calculating net worth?
Add the value of your assets, including savings, investments, retirement accounts, real estate, vehicles, and business interests. Then subtract liabilities such as mortgages, auto loans, student loans, and credit card balances.
What should I do if my net worth is below the median at age 51?
Focus on actions you can still control, such as capturing your full employer match, increasing retirement contributions, reducing high-interest debt, reviewing investment fees, and strengthening your emergency fund. A below-median net worth doesn't automatically mean you're behind because retirement needs vary considerably.
More from FinanceBuzz:
- Retire like the rich: 14 ways you could build wealth in your 50s.
- Find out if you could pay less for car insurance in just a few clicks.
- Make these 7 savvy moves when you have $1,000 in the bank.
- 14 moves seniors could benefit from but often forget about.


Intro Offer
UNLIMITED CASHBACK MATCH: Discover will automatically match all the cash back you’ve earned at the end of your first year! There’s no minimum spending or maximum rewards. You could turn $150 cash back into $300. Click Apply Now to view important rates and disclosures. Plus, receive a $200 statement credit when you spend $500 on purchases in your first 3 months of account opening
Annual Fee $0 Why we like it


